TORO Recovery Blog
30, 60, 90 or 120 Days Past Due: When Should You Escalate Collection Efforts?
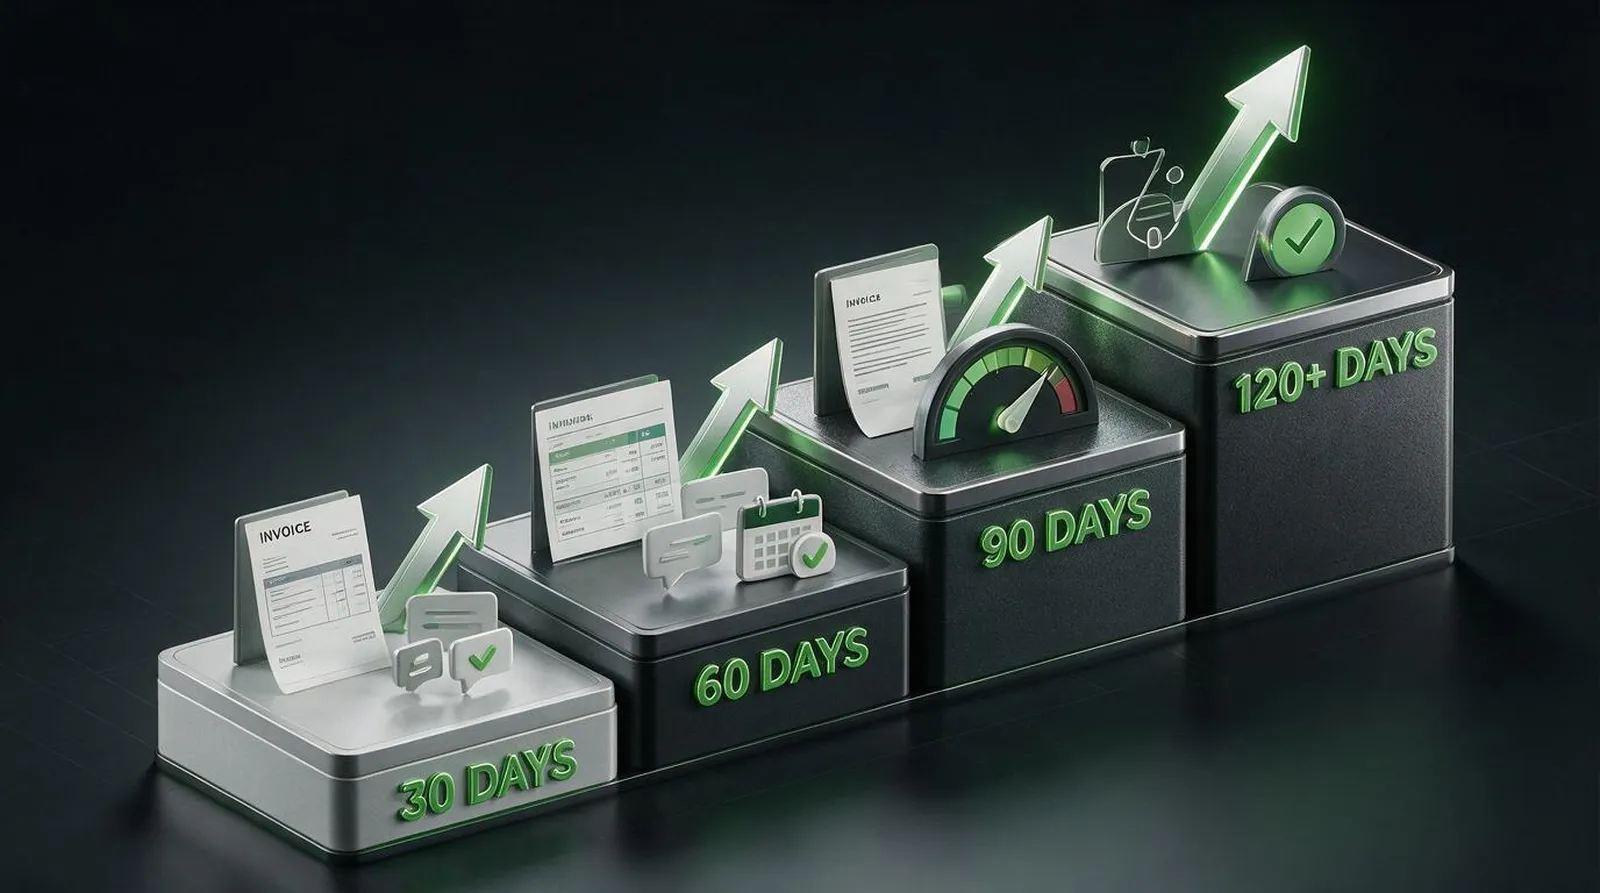
How to escalate past-due invoices at 30, 60, 90, or 120 days, with practical actions, risk signals, examples, and referral guidance for finance.
At 30 days past due, confirm the invoice and resolve administrative problems. At 60 days, move from routine reminders to a documented final demand and management-level contact. At 90 days, a supported business invoice usually deserves outside collection review unless a written payment plan is performing. At 120 days, continued internal handling should be a documented exception, not the default. These are practical escalation points, not universal legal deadlines. Contract terms, disputes, customer history, balance size, bankruptcy, state law, and filing deadlines can require a different response. Next, place every overdue account into an aging bucket, record the latest promise and dispute status, score its collection risk, and assign a dated action. Escalate sooner when the customer stops responding, breaks promises, closes locations, or shows other signs that collectability is deteriorating.
What does a past due invoice timeline measure
A past due invoice timeline measures the number of days between the invoice’s contractual due date and the current date. It does not usually measure from the invoice date. A net-30 invoice issued January 1 and due January 31 becomes one day past due on February 1. On March 2 in a non-leap year, it is 30 days past due.
An aging report groups unpaid balances into ranges such as current, 1 to 30, 31 to 60, 61 to 90, and more than 90 days past due. The report shows age, but age alone does not explain whether a customer received the invoice, disputes performance, lacks cash, or intends not to pay. A useful collection record adds the last contact, last promise, dispute status, owner, next action, and exception approval.
Toro Recovery’s definition of collection cadence explains how planned contacts, channels, timing, and escalation points work together. The cadence should begin before an account reaches 30 days past due.
What should happen at 30 days past due
At 30 days past due, verify the file and determine why payment has not arrived. Resend the invoice and statement, confirm the customer’s legal entity and accounts-payable contact, and check the purchase order, approval routing, tax documentation, portal submission, proof of delivery, and payment instructions. Ask for a calendar payment date or a specific description of the dispute.
The tone can remain cooperative when the customer has a credible administrative explanation. The account should still have an owner and a deadline. “It is being processed” is not a payment date. If the customer misses a confirmed date, stops communicating, or repeats requests for documents already provided, move to formal escalation rather than restarting the courtesy cycle.
Payment terms come from the agreement and applicable law, not from a universal net-30 rule. Federal prompt-payment regulations offer a limited illustration: covered federal agencies generally follow the contract date and, in specified circumstances, use 30 days after the payment period starts; the same rule also addresses proper invoices and automatic late-payment interest. [1] That federal framework does not set ordinary private B2B terms.
What should happen at 60 days past due
At 60 days past due, the account should leave the ordinary reminder queue. Escalate beyond the day-to-day accounts-payable contact to the customer’s controller, finance leader, owner, or business sponsor. Send a consolidated package containing the agreement, invoice, statement, performance evidence, prior acknowledgments, and the exact balance. Correct any error before making a final demand.
A final demand should state the amount, basis, payment instructions, response date, and next authorized step. Use the guidance in How to Write a Demand Letter for an Unpaid Business Invoice to keep the notice factual and supported.
If the customer proposes installments, require a written plan with amounts, dates, payment method, authority, and default terms. Keep the account in the 60-day workflow only while the plan performs. A missed first installment or vague request for more time should trigger the next review. Do not threaten litigation, credit reporting, a lien, or added fees unless the statement is accurate, authorized, and supported by the contract and law.
What should happen at 90 days past due
At 90 days past due, a supported commercial invoice should normally receive an outside collection or legal review. Internal handling can continue when a documented dispute is being resolved on schedule or a signed plan is current, but someone with authority should approve the exception and the next review date.
Prepare the referral before the final internal deadline expires. Include the contract, credit application, purchase order, invoices, account ledger, delivery or completion evidence, communications, dispute history, demand and delivery record, debtor contacts, guaranty documents, and known insolvency facts. A complete package lets an agency or attorney evaluate liability, collectability, jurisdiction, and cost without repeating weeks of internal requests.
The broader B2B Debt Collection guide explains placement, documentation, negotiation, and legal escalation. Select the path before the account ages into the next bucket.
What should happen at 120 days past due
At 120 days past due, continued internal reminders rarely need to be the default. The business should have a clear reason for waiting, such as a performing settlement, a documented operational review with a near-term decision date, a standstill approved by counsel, or a bankruptcy process. Otherwise, refer the account, obtain legal advice, or make a documented economic decision to write it off and monitor it lawfully.
Do not confuse an accounting write-off with forgiveness or the end of legal rights. Accounting treatment, tax treatment, collection activity, and litigation deadlines are separate questions. IRS guidance states that a business bad debt deduction depends on worthlessness and other tax requirements; a taxpayer must establish reasonable collection steps, but court action is not necessary when a judgment would be uncollectible. [2] Ask a qualified tax adviser how the rules apply to the business and accounting method.
How do the four stages compare
Age | Primary objective | Minimum action | Move sooner when |
|---|---|---|---|
30 days | Find and fix the cause | Verify receipt, documents, dispute, and payment date | A promise breaks, communication stops, or financial warning signs appear |
60 days | Create a formal decision point | Escalate contacts and send a supported final demand | The customer cannot state a credible source or date for payment |
90 days | Protect recovery options | Complete agency or attorney review unless an approved plan performs | The balance is material, evidence may disappear, or a deadline may be near |
120 days | End passive internal handling | Refer, seek counsel, settle, or document a write-off decision | The debtor is closing, transferring assets, dissolving, or entering bankruptcy |
The economic reason for a consistent timeline is straightforward. The Federal Reserve Banks’ 2024 payments report found that roughly four in five small firms faced customer-payment challenges, with slow-paying customers especially relevant in several B2B-heavy industries. [3] The 2026 Small Business Credit Survey reported that 50 percent of employer firms experienced uneven cash flow, a category that includes collecting receivables. [4] These survey results do not predict the outcome of a particular account, but they show why overdue balances deserve active management.
Which risk signals should override the aging bucket
Age is a lagging indicator. A newer invoice can require immediate attention when facts suggest that the customer’s ability or willingness to pay is changing. Apply the same risk criteria to every account and record the evidence behind an accelerated referral.
Risk signal | What to verify | Timing response |
|---|---|---|
Broken promise | Promised amount, date, reason missed, and proposed cure | Advance one stage unless the explanation is documented and credible |
Silence or returned communications | Contacts, address, legal entity, business status, and sponsor | Shorten the next deadline and prepare referral documents |
Late or unsupported dispute | Specific line items, contractual basis, and evidence | Investigate promptly; do not allow a vague dispute to freeze the account |
Closure, layoffs, lawsuits, or vendor complaints | Reliable public or customer information and current operations | Seek professional review without waiting for the next bucket |
Large or concentrated balance | Exposure relative to cash flow, credit limit, and customer group | Require management approval for every extension |
Possible filing or lien deadline | Governing contract, claim type, jurisdiction, and date | Send to qualified counsel immediately |
How should disputes and promises affect escalation
A genuine dispute changes the work, not the need for a deadline. Ask the customer to identify the amount disputed, the contract provision or performance issue, and the supporting documents. Assign the operational owner who can investigate. Pay or collect the undisputed portion when the agreement and circumstances allow, then set a date for the business’s written response to the remaining issue.
Promises should be measured by performance. Record the amount and exact date, then advance the account when the promise fails. A written installment plan may justify an exception if the customer has authority, the payments are feasible, and the plan states what happens after default. Repeated informal extensions make the aging report look active while delaying the decision that matters.
The collection letter generator can help standardize a final written request, but the contract, balance, remedies, and recipient information still require account-specific review.
What legal and compliance checks belong in the timeline
Before formal escalation, review the agreement’s payment, notice, cure, interest, late-fee, collection-cost, attorney-fee, governing-law, venue, arbitration, and guaranty provisions. Determine whether the claim involves goods, services, construction, government contracting, insurance, health care, transportation, a regulated license, or another field with special rules. State collection-agency licensing and conduct laws may also matter.
Confirm whether the obligation is commercial or consumer by the transaction’s actual purpose. An individual signer, sole proprietor, or personal guarantor does not by itself answer the question. If the purpose is mixed or unclear, obtain a compliance review before using a commercial workflow. Never add charges or threaten a remedy without contractual and legal support.
Bankruptcy is an immediate stop signal for ordinary collection. U.S. Courts guidance explains that a Chapter 11 filing automatically stays collection activity on prepetition debts, subject to exceptions and potential court relief. [5] Verify the case and consult bankruptcy counsel about notices, claims, collateral, and deadlines instead of sending another demand.
How can a business build a repeatable escalation policy
Write the 30, 60, 90, and 120-day actions into the credit and collection policy. Assign an owner, required evidence, contact level, communication channel, response period, and approval threshold to each stage. Define early-referral triggers and the limited reasons an account may remain internal after 90 days. Review exceptions weekly rather than allowing them to roll automatically.
At minimum, the account record should show:
Invoice date, contractual due date, days past due, balance, credits, and supported charges.
Customer entity, accounts-payable contact, operational sponsor, decision maker, and guarantor information.
Last substantive response, dispute status, promise amount and date, and whether the promise was kept.
Documents received or missing, final-demand date, delivery evidence, and outside referral readiness.
Next action, responsible owner, due date, exception reason, and approving manager.
The SBA identifies accounts receivable, available cash, and bank reconciliation among the functions a business should manage and explains the difference between cash and accrual accounting. [6] A collection policy turns those records into dated decisions. Review days sales outstanding, aging by bucket, dispute time, broken promises, and referral age together; one metric rarely explains the entire portfolio.
Use Toro Recovery’s DSO reduction calculator to estimate how a shorter collection cycle may affect cash tied up in receivables.
How would the timeline work in practice
A 30-day invoice with an administrative problem
A $4,800 invoice is 32 days past due. The customer confirms that the invoice went to an inactive email address and gives a payment-run date ten days away. Correct the contact, resend the package, and calendar the date. Keep the account internal unless the new commitment fails.
A 60-day invoice with broken promises
A $24,000 invoice is 58 days past due. Accounts payable acknowledged the balance and missed two dates. Send the final demand to accounts payable and the finance decision maker, then prepare the outside referral. Another unsupported promise should not reset the timeline.
A 90-day invoice with a partial dispute
A $72,000 invoice is 93 days past due. The customer documents a $12,000 performance dispute but does not address the remaining balance. Investigate the disputed work, demand a decision on the undisputed amount, and send the complete file for agency or counsel review based on the contract and complexity.
A 120-day invoice under a payment plan
A $36,000 invoice is 125 days past due, but the customer has made three installments on time under a signed agreement. Continue monitoring the plan under the approved exception. If an installment fails, apply the agreement’s default process and escalate without returning to courtesy reminders.
Frequently asked questions
Is 30 days past due too early for collections
Not necessarily. Thirty days may be appropriate after fraud indicators, shutdown, serious financial distress, or a broken promise. For a reliable customer with a verified processing error and payment date, internal follow-up may still be reasonable.
Should every account go to an agency at 90 days
No. A current written plan or a documented dispute with a near-term decision date may justify an approved exception. Unsupported promises and passive internal reminders usually do not.
What is the difference between due date and days past due
The due date is the contractual payment deadline. Days past due counts elapsed days after that date. An invoice can be 60 days old without being 60 days past due when the contract grants payment terms.
Does a final demand restart the aging clock
No. The aging clock continues from the contractual due date. A new agreement may change payment obligations, but a demand letter should not be treated as changing legal deadlines without qualified advice.
Can a disputed invoice be referred
Yes, but disclose the dispute and provide the evidence and response history. Correct clear errors first. Legal review may be more appropriate than ordinary agency placement when the dispute involves contract interpretation, counterclaims, or substantial exposure.
What if the customer makes a partial payment
Apply the payment accurately, confirm the remaining balance, and document whether a plan exists. Do not assume that partial payment changes a limitation period or other legal right; those rules vary.
When should an attorney review the account
Seek counsel promptly for approaching deadlines, substantial or complex disputes, secured claims, liens, arbitration, multi-state issues, bankruptcy, suspected fraud, asset transfers, or a contemplated lawsuit.
What should you do next
Run the aging report and assign every overdue balance to a 30, 60, 90, or 120-day action. Confirm the due date and file at 30 days, issue formal escalation at 60, complete outside review at 90, and require an approved reason for any internal handling at 120. Apply earlier triggers whenever collectability or a deadline may be deteriorating.
For a deeper timing decision, read How Long Should You Wait Before Sending an Unpaid Invoice to Collections. If a supported business account has reached its referral point, prepare the contract, invoices, ledger, performance evidence, contacts, disputes, and demand history before requesting professional collection review. This article provides general information, not legal, tax, or accounting advice.
Sources and references
[1] Electronic Code of Federal Regulations, 5 CFR § 1315.4. Federal prompt-payment standards used as a limited government-contracting example.
[2] Internal Revenue Service, Topic No. 453, Bad Debt Deduction. Federal tax guidance on worthlessness and reasonable collection steps.
[3] Federal Reserve Banks, 2024 Report on Payments. Small Business Credit Survey findings on customer-payment challenges.
[4] Federal Reserve Banks, 2026 Report on Employer Firms. Current survey findings on uneven cash flow, including collecting receivables.
[5] United States Courts, Chapter 11 Bankruptcy Basics. Court guidance on the automatic stay and creditor claims.
[6] U.S. Small Business Administration, Manage Your Business. Bookkeeping, accounting-method, accounts-receivable, and available-cash guidance.