TORO Recovery Blog
How Much Does B2B Debt Collection Cost? Fees, Commissions and Legal Costs Explained.
Compare B2B collection fees, contingency commissions, legal costs, and net recovery to choose the right approach for collecting unpaid business debts.
B2B debt collection usually costs a percentage of money recovered, not a percentage of the balance placed. For ordinary domestic commercial accounts, a planning range of roughly 20% to 35% is common, while small, old, disputed, previously placed, international, or legal accounts may reach 35% to 50% or more. These are market benchmarks, not a regulated national tariff; every provider's written agreement controls. Litigation can add attorney fees, filing and service charges, discovery, local counsel, investigation, and judgment-enforcement expenses. Whether any cost can be charged to the debtor depends on the contract and applicable law. Next, compare quotes using expected net recovery, define direct-payment and legal-referral fees, identify every out-of-pocket cost, and require approval thresholds before work begins.
How much do commercial collection agencies charge
Most commercial collection agencies quote a contingency commission: the agency retains an agreed percentage of money it recovers and remits the balance to the creditor. A straightforward, well-documented domestic account may receive a lower rate than a small, aged, disputed, international, or previously placed claim. Volume, average balance, account age, debtor location, documentation, and the need for legal action all influence the quote.
A reasonable budgeting benchmark is about 20% to 35% for many ordinary B2B placements, with difficult categories often quoted at 35% to 50% or more. That range is descriptive, not guaranteed. Published commercial schedules illustrate the variation: one provider lists rates from 20% for fresher accounts to 45% for international claims, while another lists 20% for larger domestic accounts placed within 120 days and higher rates for older or international files. [1] [2]
Toro Recovery's definition of a contingency fee explains the basic model. Always confirm what counts as a recovery and when the commission is earned.
What does no collection no fee actually mean
In a true contingency arrangement, no commission is due if the agency recovers nothing. It does not necessarily mean the placement has no possible cost. The agreement may separately address litigation deposits, filing fees, service, searches, bank charges, translation, international work, returned payments, account withdrawals, or other approved expenses.
The contract should also explain direct payments. If the debtor pays the creditor after placement, many agreements treat that payment as recovered through the agency and charge the commission. The same question arises when the creditor accepts merchandise, a credit, a setoff, a property transfer, or a settlement outside the agency. Define the treatment before placement so the parties do not dispute the fee after money arrives.
Which collection fee model fits your accounts
Fee model | How it works | Best fit and main tradeoff |
|---|---|---|
Contingency commission | Provider earns a percentage of amounts recovered | Aligns payment with results; rate and covered receipts must be clear |
Flat fee | Fixed price for a letter, batch, workflow, or defined service | Predictable cost; creditor may still bear recovery risk |
Hourly | Time billed at agreed professional rates | Useful for legal analysis or disputes; total cost is less predictable |
Hybrid | A reduced contingency plus a fixed, hourly, or milestone charge | Can fit complex portfolios; requires careful comparison |
Subscription or portfolio | Recurring fee for a volume of accounts or services | May suit steady placements; unused capacity can reduce value |
The label does not determine value. Compare the scope of work, minimum account size, placement requirements, escalation rules, reporting, remittance timing, cancellation rights, and excluded services. A low rate can be expensive if the provider works slowly, lacks relevant coverage, or sends every difficult matter into a higher-fee channel.
What factors increase a collection agency commission
Older invoices, because delay often reduces available records and payment options
Small balances, because core handling work may be similar regardless of claim size
Prior placement, broken settlements, or repeated unsuccessful internal contacts
Disputes involving performance, pricing, offsets, warranties, or contract interpretation
International debtors, foreign language needs, or cross-border legal questions
Missing contracts, proof of delivery, correspondence, or a reliable account ledger
Litigation, local counsel, asset investigation, or judgment-enforcement work
The timing guide How Long Should You Wait Before Sending an Unpaid Invoice to Collections explains why a documented escalation calendar can protect both recovery prospects and cost.
Why can earlier placement reduce the quoted rate
Fresher accounts often present a cleaner collection problem. Contacts are more current, the people who approved the transaction may still be available, documents are easier to retrieve, and the debtor may have more options for resolving the balance. As an account ages, the provider may need more research, repeated outreach, dispute development, or legal review. That additional work and risk can appear in a higher commission category.
Earlier placement does not mean sending every late invoice to an agency immediately. A creditor should first confirm delivery or performance, issue accurate statements, address administrative disputes, and complete its promised internal escalation. The aim is to avoid months of unstructured follow-up after the account has clearly stalled.
Toro Recovery's collection letter generator can help standardize a final internal notice before placement. Preserve the letter, delivery evidence, debtor response, and updated ledger in the claim file.
What charges can appear beyond the commission
Request a written list of every potential charge. Depending on the provider and account, additional items can include onboarding, minimum placement, skip tracing, corporate records, credit data, returned payments, bank wires, card processing, translations, international taxes, attorney referrals, court costs, service, investigators, depositions, experts, liens, garnishments, levies, and execution expenses. Some are included; others require advance payment.
Ask whether expenses are deducted before or after the percentage is calculated. On a $20,000 recovery with a 25% commission and $1,000 of approved costs, a fee calculated on the gross recovery produces a $5,000 commission and $14,000 net. If costs are deducted first and the percentage applies to $19,000, the commission is $4,750 and the net is $14,250. The contract should remove that ambiguity.
How much does a collection attorney cost
Collection attorneys may charge contingency, hourly, fixed, or hybrid fees. Pre-suit analysis and a demand letter may be fixed or hourly. Litigation may use an hourly budget, a percentage that changes after filing or trial, or a hybrid arrangement with both a reduced rate and a success component. Counsel may also require a cost deposit.
Attorney fees are governed by the engagement agreement, applicable law, and professional rules. ABA Model Rule 1.5 states that a lawyer may not charge an unreasonable fee and that a contingent agreement must be written, signed, and explain the percentage, expenses, and whether expenses are deducted before or after the fee. [3] State-adopted rules control the lawyer, so verify the rule in the relevant jurisdiction.
Use How to Choose a Commercial Collection Agency or Collection Attorney to decide when voluntary recovery remains proportionate and when legal strategy should lead.
What court and enforcement costs should you budget
Litigation expenses vary by court, location, number of defendants, service method, discovery, motions, trial, and enforcement. As a current federal example, the District of Montana lists a $405 civil filing fee, but state and local court fees differ. [4] The U.S. Marshals Service explains that fees may apply for authorized service of process and points to the governing federal regulation. [5] Private process servers use their own rates.
Other possible costs include certified records, transcripts, witness fees, copies, subpoenas, depositions, interpreters, experts, local counsel, mediation, searches, recording, liens, garnishment, levy, storage, and sale. Some litigation costs may be recoverable after judgment, but recoverable costs are not the same as all amounts spent. Federal law, for example, lists specific categories a federal court may tax as costs. [6]
Do not authorize suit based only on the likelihood of winning. Ask what assets appear reachable, what exemptions and senior liens may apply, how long judgment enforcement may take, which costs require approval, and when counsel will recommend stopping. A legally strong claim can still produce a poor financial outcome.
Can collection fees and legal costs be charged to the debtor
Sometimes, but never assume the full provider fee can simply be added to the balance. The contract with the debtor may authorize collection costs, attorney fees, interest, or late charges, and a statute may provide additional rights. The wording, notice, reasonableness, governing law, and court procedure matter. A clause allowing 'costs of collection' may not answer every question about a percentage commission.
Maintain a ledger that separates principal, credits, payments, contractual interest, late charges, agency commissions, attorney fees, and court expenses. Demand only amounts supported by the agreement and law. If the debtor disputes a charge, obtain legal review before continuing to state it as due.
The demand-letter guide shows how to state a balance and deadline without overstating remedies or unsupported additions.
How should you compare agency and attorney costs
Decision factor | Agency-first path | Attorney-led path |
|---|---|---|
Primary spend | Commission on recovered funds | Legal fee plus possible court and enforcement costs |
Cash required upfront | Often limited for non-legal work; verify exceptions | May include retainer or cost deposit |
Best fit | Documented account with realistic voluntary-payment path | Urgent deadline, major dispute, remedy, or asset risk |
Cost uncertainty | Rate is known, but recovery amount and timing are not | Work, procedure, opposition, and enforcement can expand |
Key approval | Settlement authority and legal-referral threshold | Pleadings, discovery, budget, settlement, and enforcement |
Use the business debt recovery calculator to compare assumptions about recovery, timing, and cost. Its result is a planning estimate, not a guarantee.
How do you calculate net recovery and effective cost
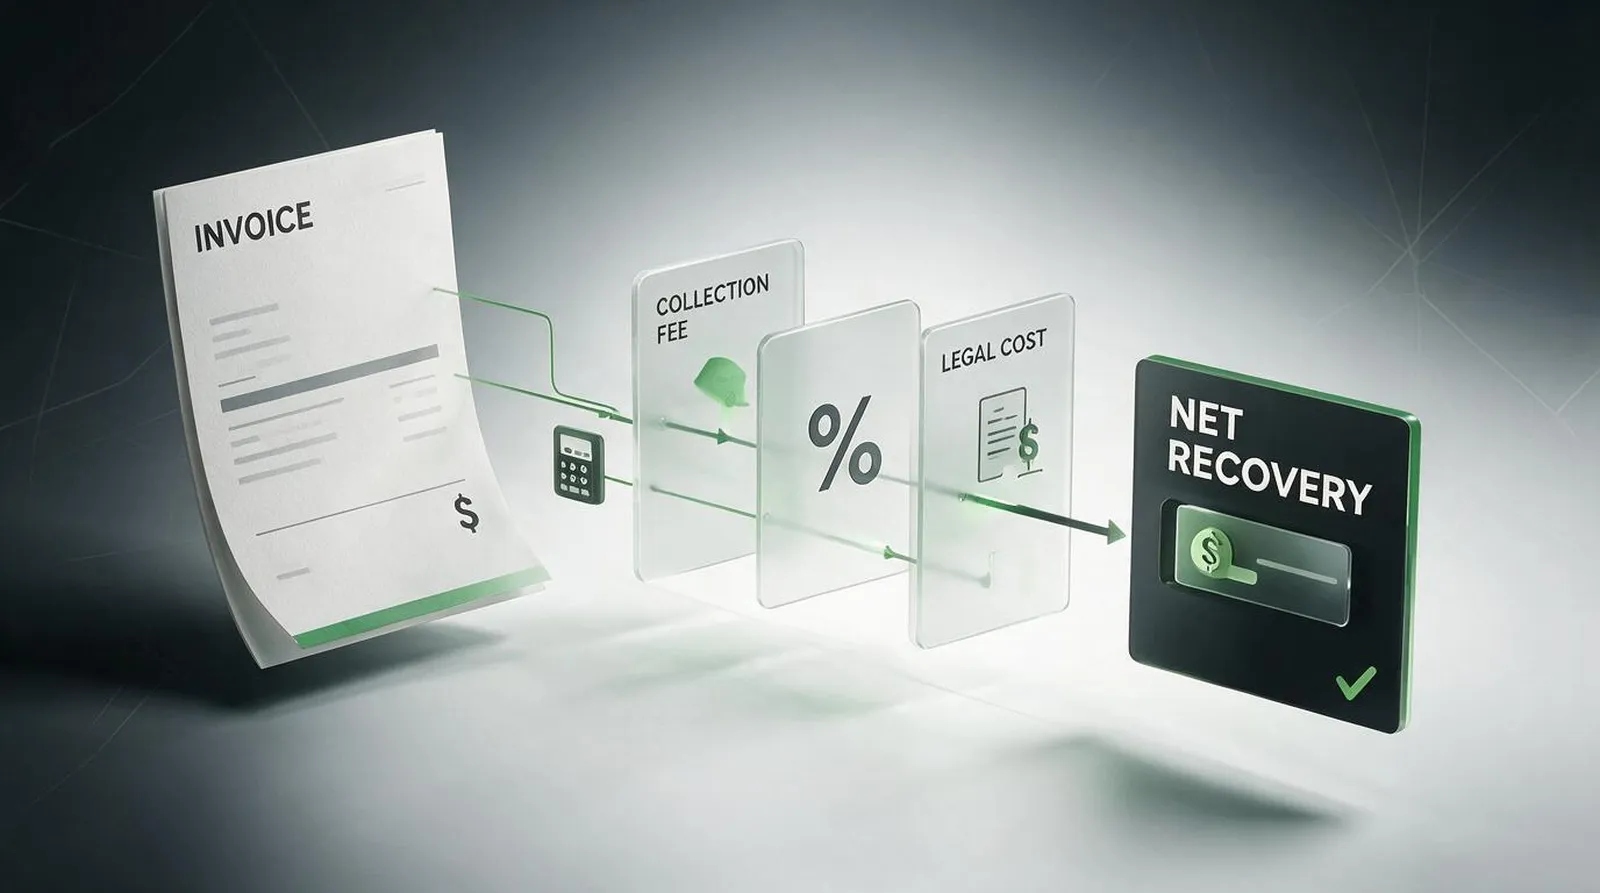
Net recovery equals cash recovered minus the commission, attorney fees, and expenses the creditor bears. Effective cost percentage equals total provider fees and creditor-paid expenses divided by cash recovered. Calculate both, because a headline commission does not capture court costs or other charges.
Example: Agency A quotes 22% and recovers $30,000 with no separate expenses, leaving $23,400. Agency B quotes 28% and recovers $40,000 with $500 of approved expenses, leaving $28,300. Agency B has the higher rate but produces $4,900 more net cash. This does not predict performance; it shows why price and recovery effectiveness must be evaluated together.
For a portfolio, compare by age band, balance band, dispute status, and placement type. Define whether recovery rate means dollars recovered or accounts resolved, whether the denominator includes withdrawn and bankrupt accounts, and how long the measurement window remains open.
What should a collection agreement say about fees
Commission percentages and every category that changes the rate
What counts as a recovery, including direct payments, credits, returns, and settlements
Whether the fee applies to principal only or to interest, charges, and other receipts
Minimum fees, flat charges, expenses, deposits, and approval thresholds
How partial payments and installment plans are allocated and remitted
Rates and responsibilities after attorney referral or litigation
Withdrawal, recall, cancellation, termination, and post-termination payments
Reporting, reconciliation, remittance timing, refunds, and audit rights
Ask the provider to illustrate the agreement using three scenarios: direct payment after placement, a negotiated payment plan, and an attorney referral. The sample calculations should show gross receipts, commission, expenses, and net remittance.
What does a practical cost comparison look like
Assume a manufacturer has ten domestic accounts totaling $180,000. Most are 120 to 210 days old and supported by contracts, invoices, and delivery records. One $55,000 account is disputed, and another debtor appears to be winding down. The creditor receives a 24% agency quote for ordinary accounts and a separate legal proposal for disputed or urgent claims.
The creditor should segment the portfolio instead of applying one fee model to every account. Ordinary claims can enter the agency workflow with 30- and 60-day review points. Counsel can assess the disputed claim and the winding-down debtor immediately. The creditor models expected net recovery, approves a court-cost ceiling, and requires written consent before suit, local counsel, an investigator, or enforcement expense.
The lowest percentage is not automatically the best outcome. The winning proposal is the one that combines relevant experience, credible workflow, transparent costs, disciplined escalation, clear reporting, and the strongest expected net recovery for the actual account mix.
Frequently asked questions
Do collection agencies charge upfront
Many commercial agencies use contingency pricing with no commission due unless they recover money. Separate expenses, flat-fee products, minimums, or legal deposits may still apply under the agreement.
What is a normal commercial collection commission
A planning range of about 20% to 35% is common for many ordinary domestic claims. Small, old, disputed, prior-placement, international, and legal accounts may be 35% to 50% or more. Obtain an account-specific quote.
Does an agency charge on the full debt or the amount collected
Contingency fees are usually calculated on money recovered, but the contract controls. Confirm treatment of interest, fees, property, credits, direct payments, settlements, and installment receipts.
Are attorney fees included in the agency commission
Not necessarily. Legal referral may trigger a different percentage, separate attorney fee, court costs, or a cost deposit. Require written approval and a clear explanation before referral.
Can the debtor be required to pay collection costs
Possibly, if the contract and applicable law support the charge. The wording, reasonableness, notices, and jurisdiction matter. Do not add the provider's fee automatically.
Should a business choose the lowest collection rate
No. Compare expected net recovery, relevant experience, timing, reporting, dispute handling, remittance controls, legal coverage, contract terms, and all additional costs.
How can Toro Recovery help you evaluate collection costs
Toro Recovery can review the account profile, identify documentation gaps, explain the proposed collection scope, and help the creditor compare voluntary recovery with attorney escalation. A useful discussion starts with balance, age, dispute status, debtor location, prior efforts, deadlines, and the creditor's settlement authority.
For the complete process, read the B2B debt collection guide. Toro Recovery can then discuss a written fee structure and account strategy based on the specific portfolio.
This article provides general business information, not legal advice or a fee quote. Pricing, licensing, contract enforceability, collection charges, attorney fees, recoverable costs, court procedure, and remedies vary by provider, jurisdiction, agreement, and facts.
Sources and references
1. New Jersey Industrial Credit Corporation, Rate Schedule and Remittance Policy
2. Stevens & Ricci, Commercial Collections Fee Schedule
3. American Bar Association, Model Rule 1.5, Fees
4. U.S. District Court for the District of Montana, Fee Schedule
5. U.S. Marshals Service, Service of Process
6. Office of the Law Revision Counsel, 28 USC 1920, Taxation of Costs