TORO Recovery Blog
Commercial Collections vs. Consumer Collections: What's the Difference?
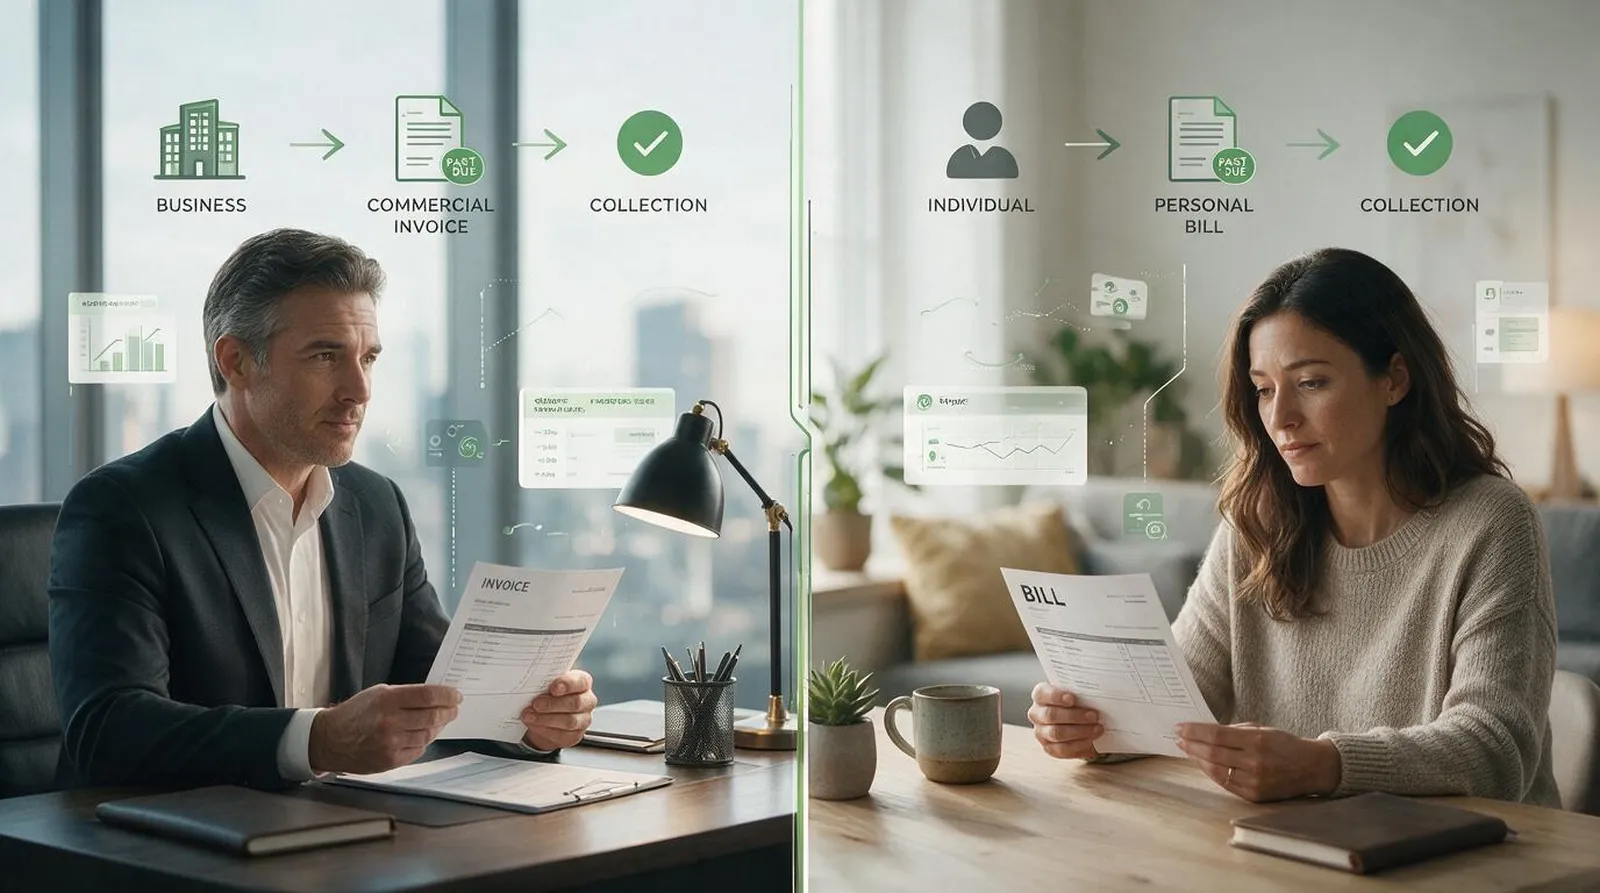
Commercial and consumer collections follow distinct rules. Learn how debt purpose, documentation, state laws, and recovery tactics shape each process.
COMMERCIAL DEBT COLLECTION GUIDE
Commercial Collections vs. Consumer Collections: What's the Difference?
How the debt type changes the governing rules, evidence, communications, and recovery strategy
Commercial collections recover business-purpose obligations, such as unpaid invoices between companies; consumer collections recover debts incurred primarily for personal, family, or household purposes. That purpose-based distinction matters because the federal Fair Debt Collection Practices Act (FDCPA) and the CFPB's Regulation F generally govern third-party collection of consumer debt, not business debt. Consumer files therefore carry specific federal rules on communications, validation information, disputes, and prohibited conduct. Commercial collection is not unregulated: contracts, statutes of limitation, court rules, bankruptcy law, state licensing laws, and state protections for certain business debts may still apply. The practical next step is to classify the transaction before collection begins, preserve the contract and account evidence, confirm the jurisdictions involved, and assign the file to a collector experienced with that debt type. [1][2]
What is the difference between commercial and consumer collections?
The difference begins with why the obligation was incurred, not simply who signed the paperwork. A consumer debt arises from a transaction primarily for personal, family, or household purposes. A commercial debt arises from a business-purpose transaction: inventory purchased for resale, freight services, equipment leased for operations, professional services delivered to a company, or an unpaid B2B invoice.
The FDCPA uses this purpose test in its definition of "debt." A natural person can therefore owe a commercial debt, as when a sole proprietor buys equipment for the business or an owner personally guarantees a company obligation. Conversely, a familiar consumer product remains consumer debt when it finances household use. Entity type, account label, and guarantor status are relevant facts, but none should substitute for reviewing the underlying transaction. [1]
Dimension | Commercial collections | Consumer collections |
|---|---|---|
Underlying purpose | Primarily business or commercial | Primarily personal, family, or household |
Typical account | Trade invoice, service contract, equipment lease, commercial loan | Credit card, medical bill, auto loan, mortgage, household service |
Federal FDCPA | Generally outside scope | Generally applies to covered third-party debt collectors |
Core evidence | Contract, purchase order, invoice, delivery or acceptance record, account ledger | Account statements, transaction history, required validation information |
Primary strategy | Resolve account-level facts while protecting business value | Follow consumer-specific communication and dispute rules |
Common decision-maker | Owner, controller, CFO, AP manager, counsel, or guarantor | Individual consumer or authorized representative |
Which debts count as commercial debt?
Common commercial claims include unpaid wholesale goods, construction or subcontractor balances, staffing invoices, freight and logistics charges, software subscriptions purchased for a company, business rent, equipment financing, and professional-service fees. The best classification evidence is usually the agreement and the surrounding transaction: the application, stated use of funds, name and delivery address, tax or business records, invoices, and communications about performance.
Mixed-use accounts require care. If a transaction served both business and household purposes, counsel may need to assess its primary purpose under the applicable law. A business name on an invoice is useful but not conclusive. Likewise, collecting from an individual guarantor does not automatically convert a business-purpose obligation into consumer debt. When classification is uncertain, a cautious collector should avoid assumptions, document the basis for its decision, and apply the stricter communication controls while obtaining legal guidance.
How do the FDCPA and Regulation F change consumer collection?
The FDCPA is the central federal statute governing covered debt collectors collecting consumer debts. Among other provisions, it addresses third-party communications, inconvenient times or places, communications after certain written requests, validation of debts, false or misleading representations, harassment, and unfair practices. Regulation F, issued by the Consumer Financial Protection Bureau, implements the FDCPA and adds detailed rules for modern communication channels and validation information. [2][3]
For a covered consumer account, the collector generally must provide validation information in the initial communication or within five days, unless an exception applies. The notice identifies the debt, creditor, amount, dispute deadline, and consumer-response options. A timely written dispute generally requires the collector to stop collecting the disputed amount until verification or a judgment copy is sent. Regulation F also addresses telephone-call frequency presumptions, email and text-message procedures, limited-content messages, and steps before furnishing information to a consumer reporting agency. [3][4]
Those federal requirements do not simply transfer wholesale to an ordinary B2B invoice. The FTC and CFPB both state that business debts are not covered by the FDCPA. Still, applying disciplined documentation, respectful communications, accurate balance information, and a meaningful dispute process to commercial files is good risk management. [2][5]
Does that mean commercial collections are unregulated?
No. Saying that the FDCPA generally does not cover business debt is not the same as saying commercial collectors have no rules. The legal framework depends on where the creditor, collector, debtor, and transaction are located, who is collecting, what the contract says, and whether litigation or reporting is contemplated.
State licensing and conduct laws can reach commercial claims. Washington, for example, requires qualifying in-state and out-of-state collection agencies to be licensed before contacting debtors there, and its statute defines a "claim" broadly as an obligation arising from an agreement or contract. California has moved further: effective for specified transactions entered into, renewed, sold, or assigned on or after July 1, 2025, its Rosenthal Act extends stated protections to certain covered commercial credit and debt of up to $500,000, subject to statutory definitions and exceptions. [6][7]
Other controls remain relevant. A collector must have a factual and contractual basis for the amount demanded; cannot misrepresent authority, legal status, or intended action; must comply with procedural rules when suing; and must respect applicable limitation periods. Contract terms determine items such as interest, late fees, collection costs, venue, notice, and attorney-fee rights, but enforceability varies by law and facts. Section 5 of the Federal Trade Commission Act also declares unfair or deceptive acts or practices in commerce unlawful, although jurisdiction, enforcement, and remedies are context-specific. [8]
Bankruptcy is a major cross-category rule. A bankruptcy petition generally triggers an automatic stay that applies to all entities and stops many actions to collect prepetition claims, whether the underlying debt is commercial or consumer. Collection activity should pause immediately when a credible bankruptcy notice appears and resume only with appropriate legal authority. [9]
How does the collection strategy change?
Consumer collection is built around standardized disclosures, privacy-sensitive contact, and statutory dispute rights. Commercial collection is usually more account-specific. The collector may need to reconstruct a transaction, identify the person with settlement authority, address a performance dispute, evaluate a personal guaranty, and preserve a viable customer or vendor relationship.
A strong commercial approach starts with a clean statement of account: what was sold, when performance occurred, what the contract required, what remains unpaid, and how the total was calculated. The first conversation should determine whether the debtor disputes liability, lacks cash, has an internal approval problem, or is strategically delaying payment. Each cause calls for a different response—documents and escalation for a dispute, verified terms for a payment plan, or prompt legal review when assets, insolvency, fraud, or limitations are concerns.
Commercial freedom should not become communication excess. Even where a consumer-specific call-frequency rule does not apply, repeated pressure can harm the claim, the brand, and settlement prospects. Accurate, proportionate, well-documented contact is both more defensible and more effective.
What documents support a commercial collection claim?
A collector can act faster when the creditor transfers a complete file. At minimum, assemble the signed agreement and amendments; credit application and guaranty; purchase orders; invoices and an itemized ledger; delivery, time, or completion records; notices of rejection or acceptance; correspondence acknowledging the balance or promising payment; credits, returns, and chargebacks; the debtor's legal name and current contact information; and any prior demand letters.
Reconcile the balance before placement. Separate principal, contractual interest, late charges, taxes, collection costs, and attorney fees. If a fee is not authorized or its enforceability is uncertain, do not present it as unquestionably due. Flag disputes, settlement discussions, bankruptcy indicators, pending litigation, and limitation concerns. Documentation quality often determines whether a file can be resolved through a business conversation or must proceed to counsel.
When should a business use a commercial collection specialist?
Account condition | Best next step | Why it fits |
|---|---|---|
Recent, undisputed, responsive debtor | Structured internal follow-up | Preserves the relationship while documenting commitments |
Repeated broken promises or avoidance | Commercial collection agency | Adds disciplined escalation and dedicated contact capacity |
Material dispute over performance or price | Evidence review and negotiated resolution | Tests the claim before increasing cost or conflict |
Large balance, asset risk, fraud indicators, or deadline concern | Prompt attorney review | Protects remedies and litigation options |
Bankruptcy filing or credible notice | Stop collection and verify with counsel | The automatic stay may prohibit continued activity |
Before hiring a provider, confirm experience with the relevant industry and account size, licensing in the necessary jurisdictions, insurance and data-security practices, dispute and complaint procedures, reporting cadence, remittance controls, fee structure, and attorney escalation process. Ask how the provider classifies debt type and handles a file when facts suggest consumer use, a guarantor, or a mixed-purpose transaction.
What do practical commercial and consumer examples look like?
Example 1: Unpaid staffing invoices
A staffing company supplies temporary workers to a manufacturer under a master services agreement. The manufacturer accepts the time records but leaves four invoices unpaid. This is a commercial claim. The recovery file should connect the agreement, approved time sheets, invoices, credits, and payment history, then address any setoff or service dispute with the controller or counsel.
Example 2: A personally guaranteed equipment lease
An owner guarantees equipment leased solely for the company's operations. The guarantor is an individual, but the purpose remains commercial. The collector should verify the guaranty's scope, notices, balance calculation, jurisdiction, and any state protections that apply to small-business or guaranteed obligations before demanding payment.
Example 3: A household medical bill
An individual incurs a bill for personal medical treatment and the provider places it with a third-party collector. That is consumer debt. The collector must evaluate the FDCPA and Regulation F, provide required validation information, honor applicable dispute procedures, protect privacy, and check additional federal and state medical-debt rules.
How should a business classify an account before placement?
Use a short intake test: Who received the goods, services, or money? What was the primary intended use? What do the application and agreement say? Is the debtor an entity, an individual, or both? Is there a guaranty? Which states are connected to the creditor, collector, debtor, and transaction? Is the claim disputed, time-sensitive, or affected by bankruptcy?
Record the answers and send them with the account. Classification should be revisited if new facts emerge. A collector that learns a supposedly commercial account financed household use should not continue on the original assumption; it should reassess the rules before further contact.
Frequently asked questions
Does the FDCPA apply to commercial debt?
Generally, no. The FDCPA defines covered debt by a primarily personal, family, or household purpose. State law or another federal law may still govern the collector, the communication, or the remedy.
Is every debt owed by a company commercial?
Usually the entity and documentation strongly indicate business purpose, but classification should still follow the underlying transaction. The purpose test is especially important for sole proprietors, mixed-use credit, and personal guarantees.
Does a personal guarantee make a B2B debt consumer debt?
Not automatically. A guarantee by a natural person can secure a business-purpose obligation. The transaction, guaranty language, applicable state law, and facts should be reviewed together.
Do commercial collectors need licenses?
Often, depending on the states and the collector’s activities. Some state collection-agency statutes cover broadly defined claims, including business debts, and may apply to out-of-state agencies contacting in-state debtors.
Can a business add collection fees or attorney fees?
Only when a valid contract or law authorizes them and the amount is enforceable. The creditor should provide the governing clause and an itemized calculation rather than assuming every collection cost can be passed through.
What happens if the debtor disputes a commercial invoice?
The collector should identify the exact dispute, pause unsupported assertions, gather the contract and performance evidence, correct genuine errors, and decide whether negotiation, expert review, or counsel is appropriate.
What is the key takeaway for creditors?
Commercial and consumer collection share the same objective—recovering a valid balance—but they do not run on the same legal and operational framework. Classify the transaction first, then match the communications, documentation, dispute process, and escalation path to the debt. For an overdue B2B account, prepare a reconciled file and consult a commercial collection provider that can confirm jurisdictional requirements before contact begins.
Legal note: This article provides general information, not legal advice. Laws change and outcomes depend on the facts and jurisdictions involved. Consult qualified counsel about a specific claim.
Sources and references
[1] 15 U.S.C. § 1692a, FDCPA definitions. Defines covered “debt” as an obligation arising primarily from personal, family, or household purposes.
[2] CFPB, What laws limit what debt collectors can say or do?. Explains FDCPA scope and states that it does not cover business debts.
[3] CFPB, Regulation F § 1006.34, Notice for validation of debts. Current regulation governing validation information and the validation period.
[4] CFPB, Debt Collection Practices (Regulation F). Rule overview, implementation materials, and official resources.
[5] Federal Trade Commission, Debt Collection FAQs. Consumer guidance confirming that business debts are outside FDCPA coverage.
[6] Washington State Department of Licensing, Collection agency licensing. Explains who needs a Washington collection-agency license, including qualifying out-of-state agencies.
[7] California Senate Bill 1286, enacted text. Extends specified Rosenthal Act provisions to defined covered commercial debt and credit, effective for specified transactions on or after July 1, 2025.
[8] 15 U.S.C. § 45, Federal Trade Commission Act § 5. Declares unfair methods of competition and unfair or deceptive acts or practices in commerce unlawful, subject to statutory jurisdiction and remedies.
[9] 11 U.S.C. § 362, Automatic stay. Sets out the bankruptcy automatic stay and its exceptions.
Sources reviewed September 10, 2026. Verify state-specific requirements and publication links at the time of use.